Across most analyses, 2021 is a unique case. The year’s historic market conditions, a post-COVID year, led to a spending boom, a slew of investments and, arguably, a number of overvaluations. This is outlined in our most recent edition of The Deal, where the broader UK equity market in 2021 saw almost £30b across just under 8000 rounds, compared to 2023’s 6,885 deals worth £20.3b.
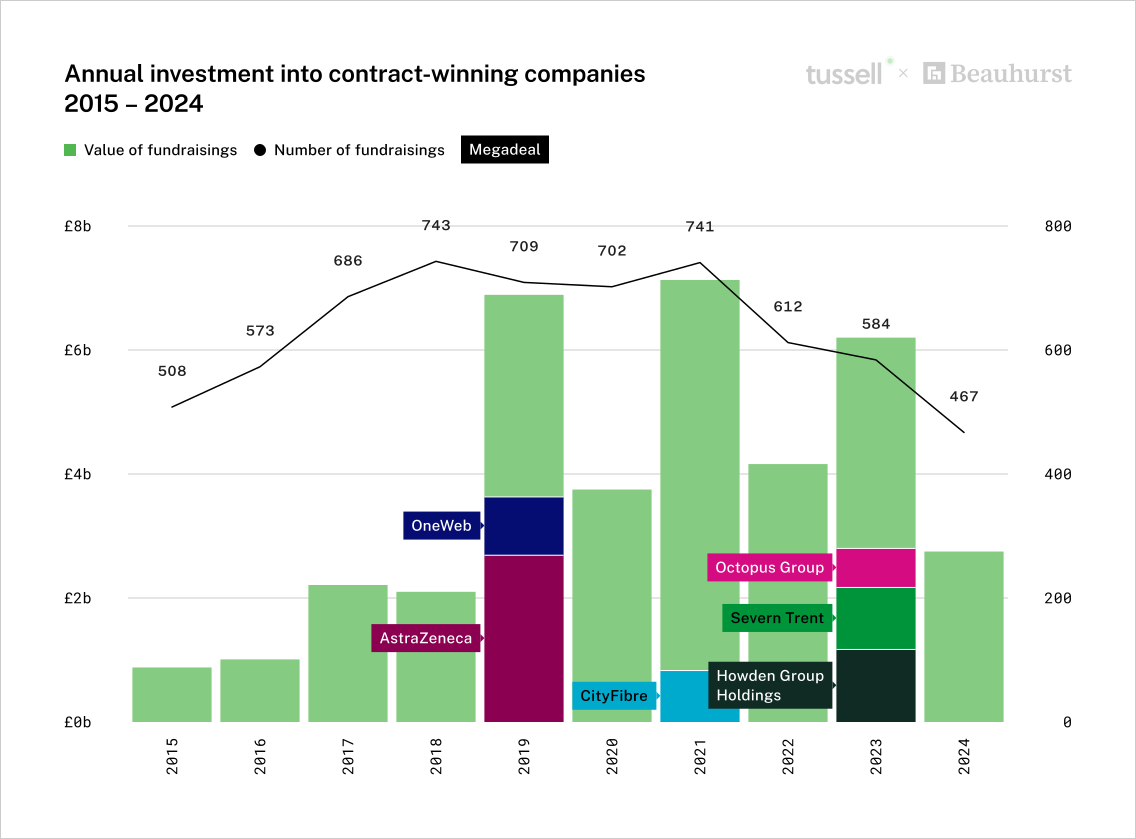
As we’ve demonstrated, the £6.20b invested into government suppliers in 2023 represents a smaller but nonetheless significant segment of the market. Some of this investment will have come before the company begins working with the public sector, with the equity investment helping to build the capacity and scale necessary to become an approved supplier. Others will have raised funding following those contracts, with investors viewing government backing as strengthening the company’s market position, and therefore a sign of a less risky investment.
Our data also reveals that Venture-stage companies are the most likely to raise (30.7%), with Seed-stage companies comprising 6.64% of deals completed.
And of the 6,325 deals completed in the last decade, only 45.2% were publicly reported, leaving almost 3,500 unannounced. We can reveal this figure using Beauhurst, the only data platform that tracks both announced and unannounced deals.
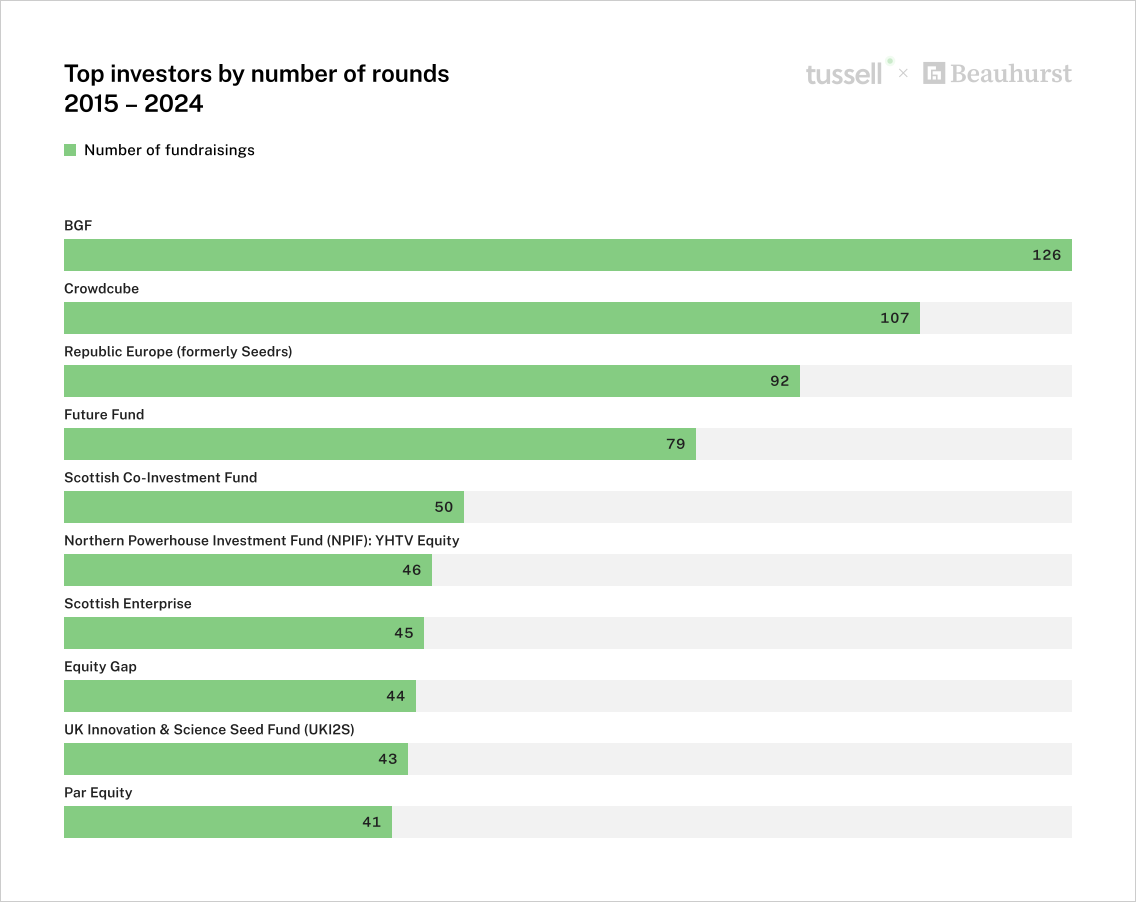
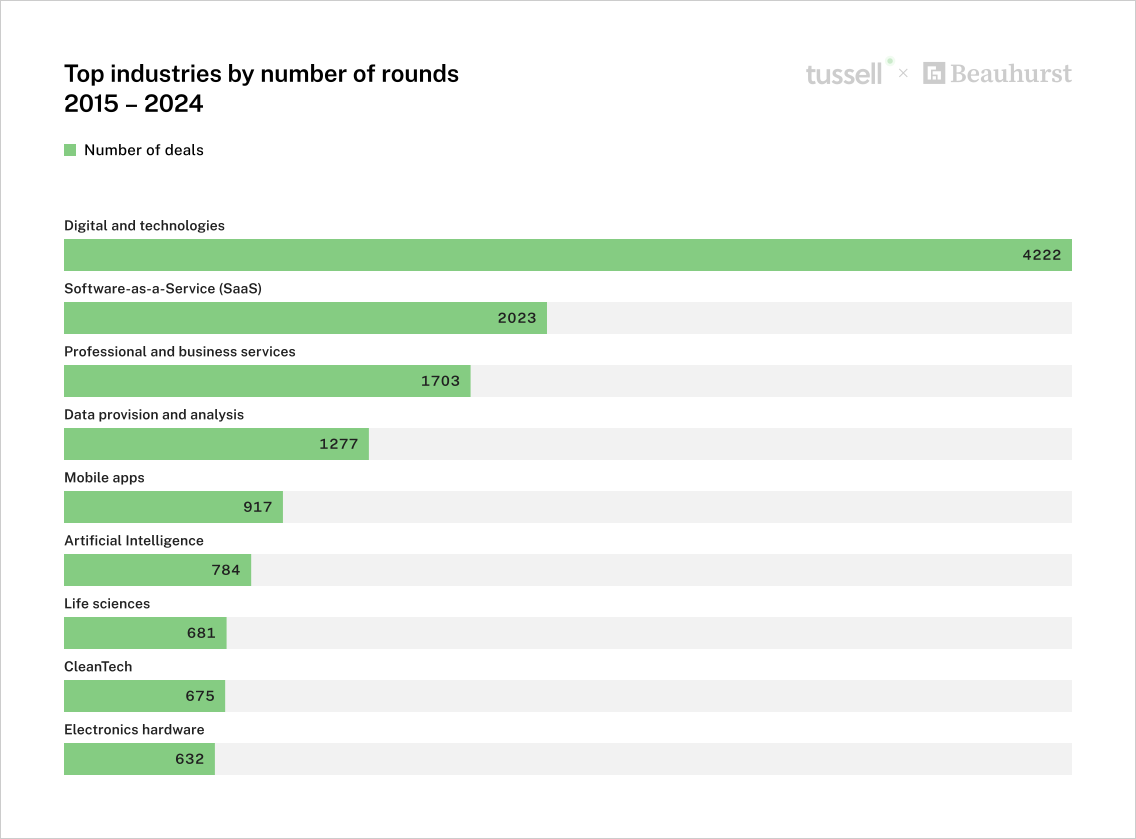
Who’s investing and which industries are they investing in?